

Varo Bank: Online Banking

- 32.95K Reviews
- 4.5
- Downloads
- 5,000,000+
Our take on Varo Bank: Online Banking from Appgk
I approached Varo Bank: Online Banking as something more demanding than a quick money-management download. A finance app can feel impressive during its first few days, yet become irrelevant once the novelty wears off. What matters is whether it makes ordinary banking easier month after month, without creating another chore to supervise. In my experience, Varo is most interesting when used as a practical everyday account: checking balances, receiving income, handling routine spending, and looking for a little flexibility when timing gets uncomfortable.
It is a free finance app from Varo Bank, N.A., aimed at people who want mobile banking with early-payday and cash-advance options. The app is rated for Everyone, runs on Android 10 or later, and its current version is 4.39.0. Its scale is also worth noting: it has passed five million installs, with an average rating of 4.5 from roughly 245 thousand ratings. Those figures suggest that this is not an experimental budgeting tool; it is an established banking product that many people use as part of their regular financial routine.
From an appealing first week to a useful long-term habit
Why the first few days feel practical
The strongest first impression comes from having several banking needs gathered in one mobile experience. Instead of treating a checking account, an occasional advance, and access to incoming pay as completely separate tasks, Varo presents them as parts of the same relationship. That can be especially appealing if your current bank feels slow, fragmented, or designed mainly around branch visits.
I can imagine a realistic first-week scenario clearly. You open the app after work to check whether a scheduled payment will leave enough room for groceries, notice when your income is available, and use the same place to review recent activity. If a short gap appears before payday, the possibility of a cash advance may feel more useful than searching for a separate service. The important point is not that every user will need each option immediately, but that the app is built around the timing problems people actually encounter.
Best Parts of Varo Bank: Online Banking
Things to Keep in Mind About Varo Bank: Online Banking
The no-fee positioning also changes the first impression. It makes the product easier to consider than a bank account that seems to punish every small action. Still, I would not interpret “no-fee” as a reason to stop reading the terms of any advance or account service. Financial convenience is valuable only when I understand the conditions attached to it and can repay what I use without turning a temporary solution into a recurring problem.
Who gets the most from the setup
Varo makes the most sense for someone who prefers to manage money from a phone and wants a straightforward alternative to a traditional bank account. It is a particularly natural fit for people whose income and bills are already handled digitally. Someone paid on a regular schedule may appreciate having an account designed around earlier access, while a person with irregular income may value the ability to see the current position quickly before committing to a purchase.
News and Features Related to Varo Bank: Online Banking

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
It can also suit a user who wants a separate account for controlled spending. I would use it that way only after deciding what role the account should play. For example, it could become the place for recurring household expenses, everyday purchases, or income deposits. Assigning one clear purpose makes the balance easier to interpret than opening an account without a plan and then wondering why the app has not improved financial organization.
On the other hand, Varo is not automatically the right choice for someone who wants a full branch-based relationship, complex business banking, or extensive face-to-face support. A person who regularly handles unusual transactions or prefers speaking with a banker may be happier with a conventional institution. Likewise, if you already have a bank that provides everything you need and you rarely care about early access or short-term flexibility, adding another account may create more administration than value.
Don't want to read the full review?
What I would check before moving important money
During setup, I would avoid transferring all of my money immediately. I would first test the basic rhythm: how easily I can find the available balance, recognize a recent transaction, and understand when an incoming payment becomes usable. This is a simple but important trial because an account can offer attractive features while still feeling awkward for the small actions repeated several times a week.
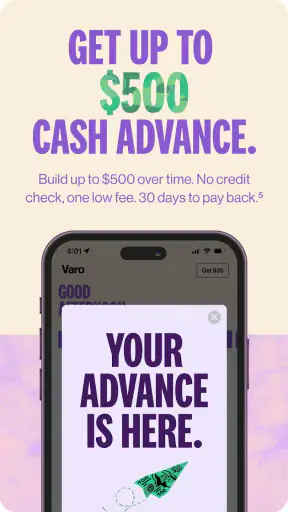
I would also decide in advance how I will treat cash advances. The healthiest workflow is to regard one as a backup tool, not as an extension of regular income. Before accepting one, I would check the amount, repayment timing, and the effect on the next pay cycle. That habit protects the long-term usefulness of the account. A feature intended for an occasional shortfall becomes stressful when it is used to cover a permanent gap between earnings and spending.
Screenshots
The month-to-month value is quieter than the launch appeal
After the first week, the app has to earn its place through repetition. The most durable value is not the excitement of opening a new account; it is the reduced friction of routine checks. If I can review activity before a bill is due, confirm that income arrived, and make a decision without navigating unnecessary complexity, the app continues to justify its space on my phone.
This is where Varo’s banking identity matters more than its promotional-sounding features. A cash advance may attract attention at first, but regular account visibility is what determines whether I keep using the app. The practical test is simple: does opening it help me make a better decision about money today? If the answer is yes several times each month, the product has recurring value even when I never use an advance.
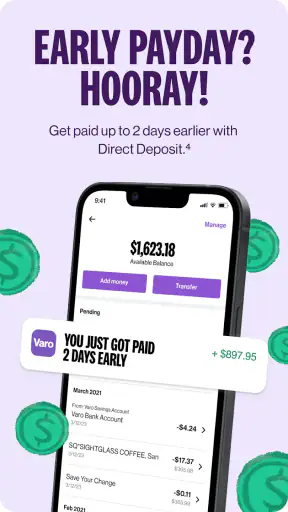
Early access to pay can also have lasting value when it improves timing rather than increasing spending. Suppose a utility payment is due just before the usual payday. Receiving income earlier could help avoid a late payment or an uncomfortable balance check. But I would still treat that access as a scheduling convenience, not extra earnings. The money remains the same; only the timing changes. That distinction is easy to overlook when an app makes earlier availability feel like a new source of cash.
A useful workflow for avoiding financial drift
My preferred routine would be to check Varo at two deliberate moments: after income arrives and before the largest recurring payments leave. At the first check, I would separate money needed for essentials from money available for discretionary use. At the second, I would confirm that the remaining balance matches the upcoming commitments. This is more effective than opening the app repeatedly without a question in mind.
A second useful habit is to review transactions when something looks unfamiliar rather than waiting until the end of the month. Mobile banking is most helpful when it shortens the distance between an event and my response. A quick review can reveal a forgotten subscription, a duplicate-looking purchase, or a spending pattern that is easier to correct now than after several weeks.
A less obvious trade-off is that a convenient mobile account can make money feel more available than it really is. Fast access and a clean interface may encourage frequent checking, but they do not replace a spending plan. I would keep a small personal buffer and avoid treating the visible balance as fully spendable. The balance tells me what is present; it does not automatically tell me what is already promised.
Maintenance is light, but not absent
Varo is not a set-and-forget financial solution. Any banking app requires regular attention to security, transaction accuracy, incoming payments, and repayment obligations. The maintenance burden is reasonable if I use the app as a central account, but it grows if I combine it with several other banks and payment services. Each additional account creates another balance to reconcile and another place where an important notification might appear.
I would keep the app updated and make sure the phone itself is protected, especially because this is a banking product rather than a casual utility. I would also review account activity on a predictable schedule instead of relying entirely on alerts. Notifications can be useful, but they are not a complete financial review. A message may tell me that something happened; I still need to decide whether it was expected and whether the remaining balance supports my plan.
The most important maintenance task concerns advances. If I use that option, I would record the repayment in my personal budget immediately. That prevents the common mistake of remembering the amount borrowed but forgetting that the next income cycle will be smaller after repayment. In my view, this is the central discipline required by Varo: convenience should be paired with a clear calendar.
Where fatigue can appear over time
The first source of fatigue is financial multitasking. If I use Varo for everyday banking, another institution for savings, a card for subscriptions, and a separate service for short-term borrowing, the app may simplify one part of my life while adding another layer to the whole system. Varo works best when its role is defined. It works less well when I expect one app to solve every financial problem without changing my habits.
The second source is dependence on early access. Once earlier availability becomes part of my normal spending plan, a delay or change in timing could feel more serious than it should. I would build my budget around confirmed income rather than the earliest possible arrival. That approach preserves the feature as a convenience instead of making it a condition for paying ordinary bills.
Cash advances create a similar tension. They are useful precisely because they address a short-term shortage, but frequent use can signal that the underlying budget needs attention. I would skip the feature entirely if I know I am likely to borrow again before the previous gap has been resolved. In that situation, a traditional bank account paired with a realistic spending plan may be a better long-term answer, even if it feels less immediately flexible.
There is also a support expectation to consider. Digital banking is efficient when the issue is routine, but people who need extensive personal guidance may find a mobile-first relationship less comfortable than a local bank or credit union. That is not a flaw unique to Varo; it is a basic trade-off of choosing app-centered banking. The convenience comes from doing more yourself, so I would choose it only if I am comfortable taking responsibility for those decisions.
How it compares with ordinary alternatives
Compared with a conventional checking account, Varo’s appeal is its emphasis on mobile access, earlier pay timing, and short-term flexibility. A traditional bank may be preferable if branch access, a broad range of account types, or established in-person service matters more to me than app-based convenience. The better option depends less on which product sounds more modern and more on how I actually handle money.
Compared with a standalone cash-advance service, keeping banking and potential advances together may reduce the number of financial relationships I need to monitor. That does not automatically make borrowing safer. The same repayment discipline applies, and I would still compare the practical terms before accepting money. The advantage is organizational; it is not permission to borrow casually.
Compared with a budgeting app, Varo is closer to an account I can use for real banking activity than a separate planning dashboard. A budgeting tool may offer a better overview across multiple accounts, while Varo can be more direct for checking its own balance and handling its own services. Someone focused on household-level planning across several institutions may need both categories, but someone seeking a single mobile banking home may prefer Varo’s narrower purpose.
Who should skip it
I would skip Varo if my main requirement is a physical branch, highly specialized financial products, or a single platform for complicated finances. I would also avoid making it my primary account if I am not prepared to monitor repayment dates and incoming money carefully. The app can make short-term decisions easier, but it cannot remove the consequences of spending more than I earn.
I would be cautious if my current bank already gives me early access, reliable mobile banking, and a comfortable emergency buffer. In that case, the benefit of switching may be too small to justify moving direct deposits, updating bill information, and learning another account’s routines. A new banking app should solve a real problem, not merely offer a different color or layout.
My long-term verdict
After the novelty fades, Varo earns lasting space when I use it for a clearly defined purpose and keep my expectations grounded. Its strongest recurring value is the combination of everyday mobile banking with earlier-payday access and a possible short-term safety net. Those tools can make a meaningful difference for someone managing tight timing between income and bills.
My recommendation is therefore conditional but positive. I would suggest it to a person who wants a free mobile banking account, understands that early access is about timing rather than extra money, and can treat cash advances as occasional backup rather than routine income. I would not recommend it as a substitute for a budget, an emergency fund, or personal judgment.
Varo Bank, N.A. has built an app that can remain useful well beyond its first-week appeal, but the user has to supply the habit that makes it work. Check the account with a purpose, plan around confirmed money, and record any repayment immediately. Follow those rules and the app feels like a practical banking companion. Ignore them and its convenience can become another source of financial noise. For the right user, that balance is worth it; for everyone else, a simpler existing bank account may be the wiser choice.
My final advice: try it as a controlled part of your financial routine before making it the center of everything. Give it a specific job, observe how well it fits your monthly cash flow, and keep borrowing separate from ordinary spending decisions. That is the best way to judge whether Varo provides lasting value rather than just an appealing first impression.
Varo Bank: Online Banking FAQ
What is Varo Bank: Online Banking, and what can I do with it?
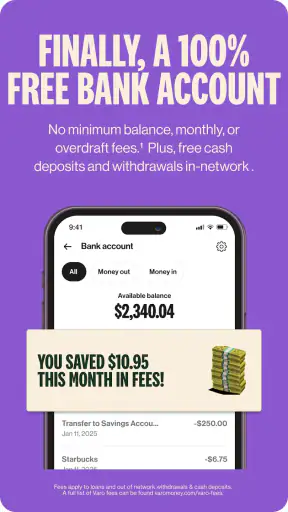
Varo Bank: Online Banking is a mobile banking app designed to let customers manage their Varo accounts from an Android or iOS device. After signing in, you can review balances and transactions, transfer money, deposit eligible checks, manage a debit card, receive notifications, and explore available banking products. The exact features you see may depend on your account type, eligibility, location, and Varo’s current terms.
Is Varo Bank: Online Banking a legitimate and secure app?
Varo Bank is a digital banking service, and its official app includes standard security features such as account authentication, device-based access controls, transaction alerts, and options for reporting suspicious activity. Before downloading, make sure the publisher is Varo Bank, N.A. and obtain the app from Google Play or Apple’s App Store. Never install unofficial versions or share your password, verification codes, or debit card details.
Can I open a Varo Bank account directly from the app?
In many cases, new customers can begin the Varo account application from within the app. You will generally need to provide personal information and complete identity verification, and approval is not guaranteed. Requirements can change, so applicants should carefully review the eligibility rules, privacy disclosures, account agreement, and fee information shown during registration. Existing customers can usually sign in after completing setup.
Does Varo Bank charge monthly fees or require a minimum balance?
Varo promotes accounts with no monthly maintenance fee and typically does not require a minimum balance for its basic banking services. However, that does not mean every possible transaction or service is free. Fees may apply in certain situations, such as using out-of-network ATMs or other optional services, and third-party charges can also occur. Review the current fee schedule inside the app or on Varo’s official website before using the account.
Can I deposit money, receive direct deposits, and withdraw cash with Varo?
Varo supports common funding and withdrawal methods, including direct deposit, transfers, eligible mobile check deposits, debit card purchases, and cash access through participating ATMs or retail locations. Availability, limits, processing times, and possible fees vary by method and account status. Mobile check deposits may require an endorsement and may be subject to holds, while ATM availability depends on the network and your location.











